Markets
How Everyday Americans Can Build a Realistic Budget That Actually Works in Real Life
A simple, flexible system that helps you control your money without feeling restricted or overwhelmed.
By Luke Graham (Personal Finance Columnist) —
Key Takeaways
- Track spending first to gain awareness before making any cuts.
- Use simple categories (Needs, Wants, Future) and automate key transfers.
- Review monthly and keep an emergency fund so the plan survives real-life surprises.
Most budgets fail because they are too rigid or too complicated.
People create detailed spreadsheets, cut every “fun” expense, and then abandon the plan within weeks. A budget that lasts is one that fits real American life—variable income, rising costs, family needs, and the occasional unexpected bill.
Start with tracking, not restricting. For two to four weeks, simply record every dollar that comes in and goes out. Use a free app, a notes file, or even a paper notebook. The goal is awareness, not judgment. Most people discover small leaks—subscriptions they forgot, frequent takeout, or convenience fees—that add up to hundreds of dollars each month.
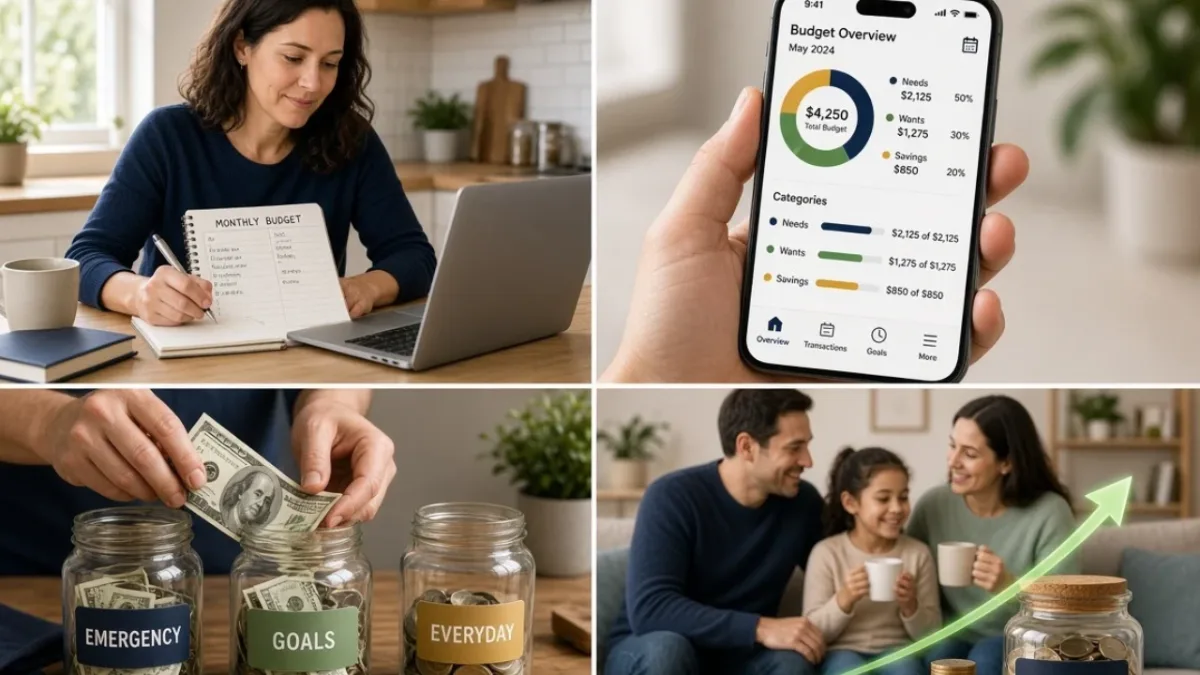
Next, separate your money into three clear categories: Needs, Wants, and Future. Needs cover housing, utilities, groceries, transportation, insurance, and minimum debt payments. Wants include dining out, streaming services, hobbies, and entertainment. Future money goes toward emergency savings, retirement contributions, and specific goals like a home down payment or vacation fund. A common starting guideline is 50% Needs, 30% Wants, and 20% Future, but the exact percentages should match your situation.
Build an emergency fund before aggressive investing or debt payoff beyond the minimums. Aim for $1,000 as a starter cushion, then work toward three to six months of essential expenses. This fund prevents new debt when the car needs repairs or a medical bill appears. Keep it in a high-yield savings account that is separate from daily spending.
Automate what you can. Set up automatic transfers for savings and retirement contributions on payday. Pay fixed bills automatically when possible. Automation removes decision fatigue and protects your priorities even on busy or stressful weeks.
Review and adjust monthly instead of daily. Life changes—raises, new expenses, seasonal costs. A quick 20-minute check each month keeps the budget current without turning money management into a constant chore. Celebrate progress, even small wins like staying under the dining-out limit or adding to savings.
A realistic budget is not about deprivation. It is about intentional choices. When you know where your money is going, you can spend on what truly matters and cut what does not—without guilt or constant calculation. That clarity is what turns budgeting from a source of stress into a tool for freedom.